Justknock Professional Social Networking Platform Logo
    • Gelişmiş Arama
  • Konuk
    • Giriş
    • Kayıt
    • Gece modu
Vishal Panchmukh Cover Image
User Image
Kapağı yeniden konumlandırmak için sürükleyin
Vishal Panchmukh Profile Picture
Vishal Panchmukh
  • Zaman çizelgesi
  • Gruplar
  • Beğeniler
  • Arkadaşlar
  • Resimler
  • Videolar
  • Makaralar
Vishal Panchmukh profile picture
Vishal Panchmukh
5 w - çevirmek

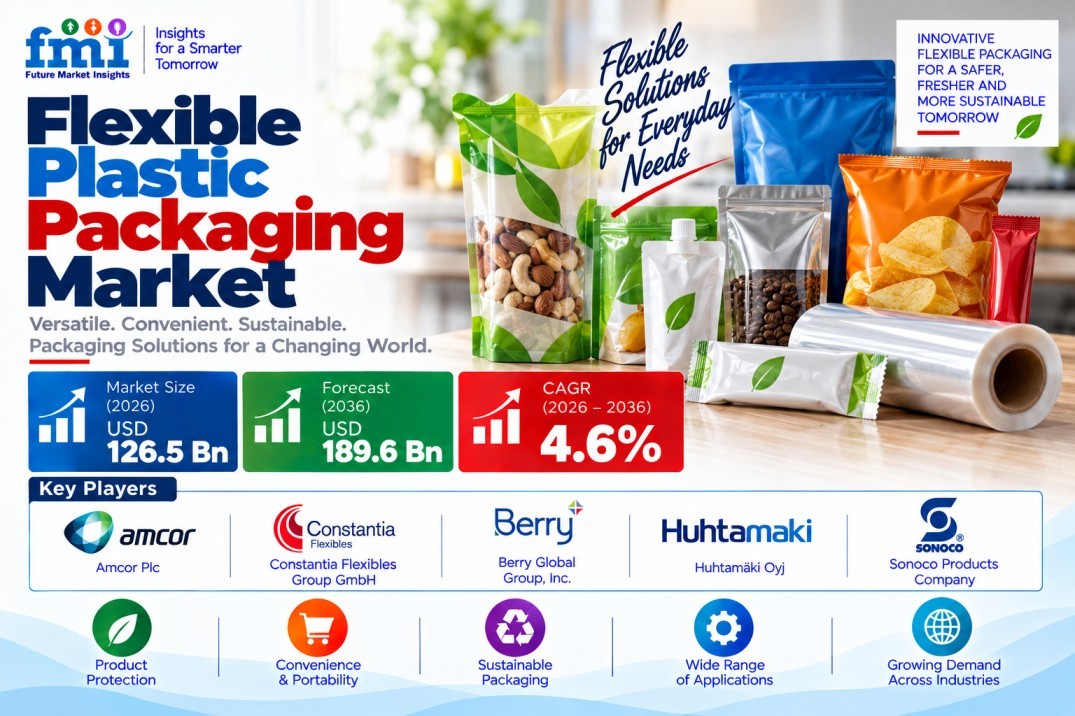
Flexible Plastic Packaging Market Estimated at USD 189.6 Bn by 2036, China 6.5%, Germany 3.5% CAGR

The global flexible plastic packaging market is projected to grow from USD 126.5 billion in 2026 to USD 189.6 billion by 2036, expanding at a 4.6% CAGR, as food, pharmaceutical, personal care, and industrial packaging demand continues to favor lightweight films, pouches, wraps, and other flexible formats.
The market's sustainability challenge has become more immediate in Europe. The European Union's Packaging and Packaging Waste Regulation (PPWR) began applying on August 12, 2026, while requirements that all packaging be recyclable apply from 2030.
That timing is pushing flexible packaging suppliers to address a difficult combination: maintaining shelf life, seal performance, and pack strength while simplifying structures and improving recyclability.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsigh....ts.com/reports/sampl
Why is flexible packaging being redesigned rather than simply replaced?
Flexible plastic packaging continues to benefit from its ability to deliver product protection with relatively low material weight. Films and wraps are expected to account for 36.8% of product demand in 2026, while oil-based polymers are projected to hold 58.0% of material demand.
Food remains a major source of volume because meat, dairy, snacks, bakery products, and fresh produce require barrier and sealing performance that can be difficult to replicate with alternative materials.
High-barrier structures are particularly important where oxygen and moisture control determine shelf life. Modified-atmosphere packaging is projected to represent 45.8% of packaging-type demand in 2026, reflecting continued use in fresh food applications.
The sustainability transition therefore is not simply a shift from plastic to another material. In many applications, converters are redesigning the plastic structure itself—reducing material weight, moving toward mono-material PE or PP formats, and testing recycled content where performance and regulatory requirements allow.
What changed for flexible packaging suppliers in August 2026?
The PPWR's application from August 12, 2026 gives the European market a more harmonized framework for packaging and packaging waste. The regulation also establishes requirements around recyclability and recycled plastic use, with key recyclability provisions applying from 2030.
For flexible packaging suppliers, this changes the commercial conversation. A film structure now has to satisfy more than the filling machine and shelf-life test. Customers increasingly need evidence around material composition, recyclability, recycled content, and end-of-life pathways.
This creates an opening for suppliers with technical capabilities in mono-material structures and recycle-ready films. It also puts pressure on multi-layer laminates where individual layers are necessary for barrier performance but complicate recovery.
Flexible packaging competition is moving toward material science and scale
The competitive landscape is becoming more concentrated around companies able to combine resin knowledge, film conversion, printing, pouch production, and customer qualification.
Amcor completed its combination with Berry Global on April 30, 2025, creating a broader consumer and healthcare packaging portfolio and identifying approximately USD 650 million in synergies.
The transaction illustrates a broader competitive pattern: scale can provide access to more technologies, geographic manufacturing capacity, and customer programs at a time when packaging buyers are asking suppliers to solve both performance and sustainability requirements.
Mondi Group, Constantia Flexibles, Huhtamäki Oyj, Sealed Air Corporation, ProAmpac, Uflex, Winpak, and American Packaging also compete across different combinations of films, pouches, food packaging, healthcare packaging, and recycle-ready structures.
The result is a market where the winning specification is increasingly defined by total pack performance rather than resin cost alone.
Analyst perspective
Ismail Sutaria, Principal Analyst at Future Market Insights, says:
“Flexible plastic packaging is no longer judged only by price per pack. I see brand owners asking for three things at the same time: shelf life, lower material weight and a clearer recycling route. The hard part is that each request changes the film structure.”
Flexible Plastic Packaging Market Snapshot
• Market Size, 2025: USD 120.9 billion
• Market Size, 2026: USD 126.5 billion
• Forecast, 2036: USD 189.6 billion
• CAGR, 2026–2036: 4.6%
• Incremental Opportunity: USD 68.7 billion
• Leading Product: Films and wraps, 36.8%
• Leading Material: Oil-based polymers, 58.0%
• Leading Packaging Type: Modified-atmosphere packaging, 45.8%
• Leading Application: Pharmaceutical packaging, 42.0%
• Fastest-Growing Country: India, 7.0% CAGR
Which countries offer the strongest growth opportunities?
India is forecast to be the fastest-growing major market at 7.0% CAGR through 2036, followed by China at 6.5%. Brazil is projected to grow at 5.5%, while the United States is forecast at 5.0%.
India's opportunity is linked to both domestic consumer demand and its expanding plastics manufacturing and export base. China retains significant scale through food processing, consumer goods, pharmaceutical manufacturing, and film conversion.
The mature markets present a different opportunity. Germany and Canada are both projected at 3.5%, making regulatory compliance, lightweighting, and premium-value applications more important than simple volume expansion.
What is driving flexible plastic packaging demand?
Lightweighting: Flexible formats can reduce packaging material and transportation weight while maintaining product protection.
Shelf-life requirements: High-barrier films help protect food, pharmaceutical, and other sensitive products from oxygen and moisture.
Refill formats: Spouted pouches and refill packs allow personal-care and home-care brands to reduce dependence on rigid containers.
Fresh food distribution: Modified-atmosphere and vacuum-based formats support longer retail windows for meat, seafood, produce, and prepared foods.
Pharmaceutical applications: Sachets, sterile pouches, and other regulated formats continue to require reliable sealing and controlled material performance.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsigh....ts.com/reports/sampl
Where does the market face the greatest pressure?
Recycling remains the central structural challenge. Flexible packaging frequently combines multiple layers because no single polymer can always deliver the required barrier, strength, printability, and seal performance.
The transition toward mono-material structures can simplify recycling but may require changes to barrier coatings, adhesive systems, seal layers, and processing conditions. Suppliers must therefore prove that sustainability improvements do not reduce shelf life or production efficiency.
Raw-material volatility is another constraint. Resin prices directly affect converter margins, encouraging downgauging and material optimization. Suppliers with strong film-engineering capabilities can respond more effectively because they can reduce material use without simply passing cost increases downstream.
About the Flexible Plastic Packaging Market Report
Future Market Insights' study analyzes flexible plastic packaging across product, material, product material type, packaging type, application, end use, and region.
The market includes pouches, bags and sacks, tubes, sleeve labels, films and wraps, high-barrier films, spouted pouches, shrink films, vacuum skin packaging, modified-atmosphere packaging, food packaging, pharmaceutical packaging, personal care packaging, industrial packaging, and agricultural packaging.
FMI Research Methodology: https://www.futuremarketinsights.com/methodology

Disclosure: This press release is based on Future Market Insights' syndicated research. Market estimates and forecasts reflect the definitions, assumptions and methodology applied in the underlying study.

Media Contact
Future Market Insights, Inc.
Christiana Corporate
200 Continental Drive, Suite 401
Newark, Delaware 19713, United States

About Future Market Insights
Future Market Insights, Inc. is a global market intelligence and consulting organization serving clients across more than 150 countries. The company is registered in Delaware as Future Market Insights, Inc., Christiana Corporate, 200 Continental Drive, Suite 401, Newark, Delaware 19713, United States, with regional operations across North America, Europe, the Middle East and India.
image
Beğen
Yorum Yap
Paylaş
Vishal Panchmukh profile picture
Vishal Panchmukh
5 w - çevirmek

Medical Specialty Bag Market Estimated at USD 9.6 Bn by 2036, China 10.2%, UK 7.9% CAGR

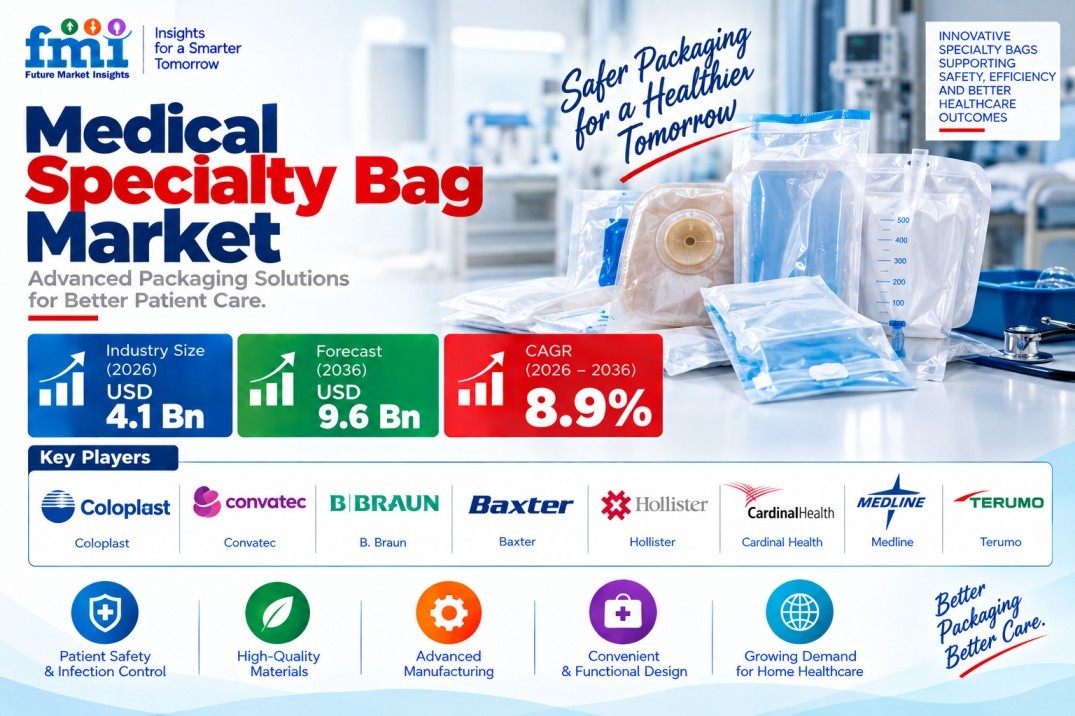
The global medical specialty bag market is projected to grow from USD 4.1 billion in 2026 to USD 9.6 billion by 2036, expanding at a 8.9% CAGR, as ostomy care, hospital fluid management, urinary drainage, and home-based treatment increase demand for specialized collection and delivery bags.

The market was valued at USD 3.8 billion in 2025. Ostomy bags are expected to hold the largest product share at 34.0% in 2026, while PVC is projected to account for 42.0% of material demand. Disposable bags are expected to represent 71.0% of the market, reflecting the importance of infection-control requirements in clinical settings.

👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends:https://www.futuremarketinsigh....ts.com/reports/sampl

Why are medical specialty bags becoming a care-continuity product?

Medical specialty bags increasingly span the entire care pathway rather than remaining limited to hospital procedures. Ostomy and urinary drainage products continue to generate recurring demand after discharge, while IV fluid, blood, drainage, and feeding bags support hospital-based treatment.

Ostomy care is particularly important because pouch replacement creates recurring purchasing requirements. Product design is also becoming more relevant to repeat selection. Convatec's February 2024 launch of Esteem Body with Leak Defense, for example, focused on pouch shape and wear performance, illustrating how manufacturers are competing on usability alongside basic fluid containment.

Homecare is adding another layer to demand. As more treatment and recovery takes place outside hospitals, patients and caregivers require products that are easier to handle, discreet, and reliable during routine use. This is shifting competition toward leakage control, skin compatibility, handling convenience, and dependable distribution.

How are supply reliability and material choices changing competition?

Hospital buyers are balancing product performance with supply continuity. Disruptions to sterile fluid availability have highlighted the importance of qualified production capacity and dependable sourcing, particularly for IV fluid bags and other products used across high-volume hospital procedures.

Material selection is also becoming a competitive consideration. PVC is projected to retain the largest share in 2026 because of its established processing characteristics and cost position, but polyolefin-based alternatives are gaining attention in selected non-PVC applications.

This creates a two-track competitive environment. Large suppliers can use manufacturing scale, regulatory experience, and broad hospital relationships to defend high-volume contracts, while specialist companies can differentiate through ostomy comfort, drainage performance, homecare support, or regional distribution.

Recent product developments reinforce the shift toward usability and material performance

In May 2024, Coloplast expanded its SenSura Mio portfolio with new ostomy pouch formats and color options, addressing patient preferences around fit and discretion.

In October 2025, B. Braun launched midazolam in sodium chloride injection in IV bags not made with DEHP and PVC, reflecting continued attention to alternative material configurations in sterile fluid delivery.

These developments show that medical specialty bag competition is moving beyond simple capacity. Suppliers increasingly need to demonstrate clinical reliability, material suitability, user comfort, and consistent supply.

Analyst perspective

Sabyasachi Ghosh, Principal Analyst at Future Market Insights, states:

“Medical specialty bags are no longer single-use hospital consumables but a care-continuity product category spanning surgery and home recovery. Demand is shaped by two forces: cost and sterility efficiency in hospitals, and comfort in homecare.”

Medical Specialty Bag Market Snapshot

Market Size, 2025: USD 3.8 billion
Market Size, 2026: USD 4.1 billion
Forecast, 2036: USD 9.6 billion
CAGR, 2026–2036: 8.9%
Incremental Opportunity: USD 5.5 billion
Leading Product: Ostomy bags, 34.0%
Leading Material: PVC, 42.0%
Leading Usage Type: Disposable bags, 71.0%
Leading End User: Hospitals, 45.0%
Fastest-Growing Country: India, 10.7% CAGR
Access detailed market insights: https://www.futuremarketinsigh....ts.com/reports/broch

Which countries offer the strongest growth opportunities?

India is projected to record the fastest growth at 10.7% CAGR through 2036, followed by China at 10.2%. Brazil is forecast to grow at 8.6%, while the United States is expected to expand at 8.4%.

The difference reflects varying healthcare access, hospital capacity, reimbursement structures, domestic medical-device production, and homecare penetration. India and China combine large patient populations with expanding healthcare infrastructure, creating opportunities across both hospital and homecare channels.

More mature markets remain important because reimbursement systems and established clinical pathways support recurring product demand. Germany is projected to grow at 7.7%, the United Kingdom at 7.9%, and Japan at 6.8%.

What is driving demand for medical specialty bags?

Ostomy care: Long-term stoma management creates recurring pouch replacement demand and supports stable homecare consumption.

Hospital fluid management: IV fluid and blood bags remain important components of sterile delivery and collection systems across hospitals.

Homecare expansion: Earlier discharge and supervised self-care shift product consumption from hospitals toward home-based settings.

Infection control: Disposable formats reduce cleaning and reuse requirements, supporting their 71.0% projected share in 2026.

Material transition: Selected applications are evaluating polyolefin and other alternatives where material safety, disposal, or regulatory considerations influence purchasing.

What constraints could limit market expansion?

The market faces pressure from material costs, regulatory requirements, infection-control expectations, and supplier qualification. Medical bags must meet demanding requirements for leakage resistance, seal integrity, sterility, labeling, and traceability.

The combination of clinical risk and regulatory scrutiny makes supplier switching more difficult than in conventional flexible packaging. Hospitals and healthcare networks generally need confidence in product consistency before expanding a new supplier across multiple facilities.

Homecare creates a different challenge. Products must remain clinically reliable while also being comfortable and simple enough for patients and caregivers to manage. Suppliers that address both requirements can build stronger positions across institutional and recurring homecare demand.

About the Medical Specialty Bag Market Report

The Future Market Insights study analyzes the medical specialty bag market across product type, material type, end user, usage type, distribution channel, and region. The forecast covers 2026 to 2036, with 2025 as the historical reference year.

The study covers ostomy bags, urinary bags, IV fluid bags, blood bags, drainage bags, and feeding bags across PVC, polyolefin, silicone, and nonwoven materials.

FMI Research Methodology: https://www.futuremarketinsights.com/methodology

Medical Specialty Bag Market: https://www.futuremarketinsigh....ts.com/reports/medic

EUDR-Compliant Pharma Secondary Carton Board Market: https://www.futuremarketinsigh....ts.com/reports/eudr-

NFC-Integrated Autoinjector Secondary Packaging Market: https://www.futuremarketinsigh....ts.com/reports/nfc-i

Tamper-Evident Pharma Serialization Labels Market: https://www.futuremarketinsigh....ts.com/reports/tampe

Disclosure: This press release is based on Future Market Insights' syndicated research. Market estimates and forecasts reflect the definitions, assumptions and methodology applied in the underlying study.

Media Contact
Future Market Insights, Inc.
Christiana Corporate
200 Continental Drive, Suite 401
Newark, Delaware 19713, United States

About Future Market Insights
Future Market Insights, Inc. is a global market intelligence and consulting organization serving clients across more than 150 countries. The company is registered in Delaware as Future Market Insights, Inc., Christiana Corporate, 200 Continental Drive, Suite 401, Newark, Delaware 19713, United States, with regional operations across North America, Europe, the Middle East and India.

image
Beğen
Yorum Yap
Paylaş
Vishal Panchmukh profile picture
Vishal Panchmukh
5 w - çevirmek

Wood Pallets Market to Record USD 4.69 Bn by 2035, India - 5.6%, Germany - 5.3%

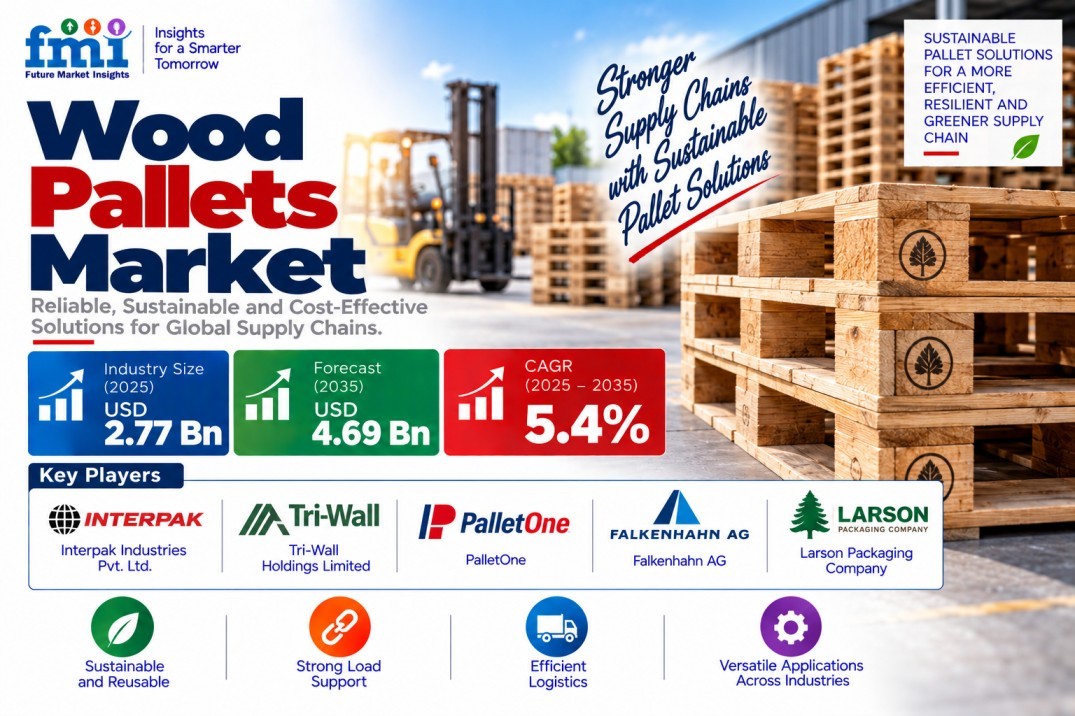
The global wood pallets market is projected to grow from USD 2.77 billion in 2025 to USD 4.69 billion by 2035, advancing at a 5.4% CAGR, as international trade, e-commerce, food and beverage distribution, and pharmaceutical logistics sustain demand for durable and compliance-ready transport packaging.

Wood pallets remain closely linked to cross-border shipment requirements because international movements of wooden packaging generally require compliance with ISPM-15 phytosanitary treatment requirements. At the same time, pallet users are placing greater emphasis on reuse, refurbishment, traceability, and responsible timber sourcing as logistics networks seek to manage material costs and sustainability targets.

👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsigh....ts.com/reports/sampl

Why are compliance and reuse becoming central to pallet procurement?

International shipping continues to make treated wooden pallets an important component of global logistics. Exporters need pallet systems that can satisfy applicable phytosanitary requirements while remaining durable enough for repeated handling, storage, and transportation.

This is creating a market where pallet value increasingly extends beyond the initial manufacturing cost. Certified timber sourcing, heat-treatment capabilities, refurbishment networks, and pallet pooling can influence total lifecycle economics for large logistics operations.

The shift toward reuse is particularly relevant as timber prices and availability fluctuate. Instead of treating pallets as disposable transport components, logistics operators can use recovery and refurbishment networks to extend pallet life and reduce the need for replacement units.

The competitive landscape includes Interpak Industries Pvt. Ltd., Tri-Wall Holdings Limited, PalletOne, Falkenhahn AG, Larson Packaging Company, INKA Paletten, PECO Pallet, Millwood, Inc., CHEP, Kamps Pallets, UFP Industries, Loscam, and WestRock Company, among other regional suppliers.

Which pallet formats and markets are creating the strongest opportunities?

Hardwood pallets are forecast to expand at a 5.8% CAGR through 2035, ahead of the overall market growth rate. Their strength and durability make them particularly relevant for heavier loads and demanding applications.

Four-way entry pallets are projected to grow at 5.6% CAGR, supported by their ability to accommodate handling from multiple sides. This characteristic can become increasingly useful as warehouses adopt automated handling equipment and seek greater flexibility in storage and movement.

Food and beverage remains an important end-use market, with pharmaceutical, automotive, electronics, manufacturing, and e-commerce logistics adding demand across different pallet specifications.

Geographically, China is forecast to record the fastest country-level growth at 6.0% CAGR through 2035. India is also positioned for expansion at 5.6%, supported by manufacturing and logistics development.

The combined growth of manufacturing, exports, warehousing, and e-commerce suggests that pallet suppliers with regional recovery infrastructure can compete on more than unit price by offering reliable supply and lifecycle services.

Analyst Perspective

Ismail Sutaria, Principal Consultant for Packaging at Future Market Insights, says:

“The wood pallets market is shifting toward compliance-ready supply and reusable logistics models. Pallet makers with certified sourcing, heat-treatment capacity, and refurbishment networks are likely to gain an advantage as exporters look for reliable packaging that meets trade rules without adding avoidable cost.”

Access detailed market insights: https://www.futuremarketinsigh....ts.com/reports/broch

Market Snapshot

Market size, 2025: USD 2.77 billion
Forecast, 2035: USD 4.69 billion
CAGR, 2025–2035: 5.4%
Hardwood pallets CAGR: 5.8%
Four-way entry pallets CAGR: 5.6%
China CAGR: 6.0%
India CAGR: 5.6%
What is driving demand for wood pallets?

International trade: Export shipments continue to require compliant wooden packaging, supporting demand for treated pallets.

Warehouse modernization: Four-way entry designs provide handling flexibility as distribution centers increase automation and optimize storage layouts.

Reuse and refurbishment: Pooling, repair, and recovery systems can help operators manage timber costs and reduce replacement requirements.

Food and pharmaceutical logistics: Products moving through regulated supply chains require dependable transport platforms capable of meeting handling and hygiene expectations.

Timber-price volatility, supply availability, competition from plastic and composite alternatives, and evolving sustainability expectations remain important considerations. These pressures are encouraging pallet suppliers to strengthen sourcing, repair, pooling, and tracking capabilities.

About the Wood Pallets Market Report

The Wood Pallets Market study examines the market by wood type, entry type, end use, and geographic market, covering applications across food and beverages, pharmaceuticals, automotive, manufacturing, e-commerce, and logistics.

The report evaluates market development through 2035, including country-level opportunities and the competitive landscape spanning global, regional, and specialized pallet suppliers.

FMI Research Methodology: https://www.futuremarketinsights.com/methodology

Wood Pallets Market: https://www.futuremarketinsigh....ts.com/reports/wood-

Recyclable Layer Pads Market: https://www.futuremarketinsigh....ts.com/reports/recyc

Beauty & Cosmetic Packaging Market: https://www.futuremarketinsigh....ts.com/reports/beaut

Aluminum-Free Retort Pouches Market: https://www.futuremarketinsigh....ts.com/reports/alumi

Disclosure: This press release is based on Future Market Insights' syndicated research. Market estimates and forecasts reflect the definitions, assumptions and methodology applied in the underlying study.

Media Contact
Future Market Insights, Inc.
Christiana Corporate
200 Continental Drive, Suite 401
Newark, Delaware 19713, United States

About Future Market Insights
Future Market Insights, Inc. is a global market intelligence and consulting organization serving clients across more than 150 countries. The company is registered in Delaware as Future Market Insights, Inc., Christiana Corporate, 200 Continental Drive, Suite 401, Newark, Delaware 19713, United States, with regional operations across North America, Europe, the Middle East and India.

image
Beğen
Yorum Yap
Paylaş
Vishal Panchmukh profile picture
Vishal Panchmukh
6 w - çevirmek

Barrier Film Market Set to Grow at 5.5% CAGR Through 2036, India Records 5.9% Growth

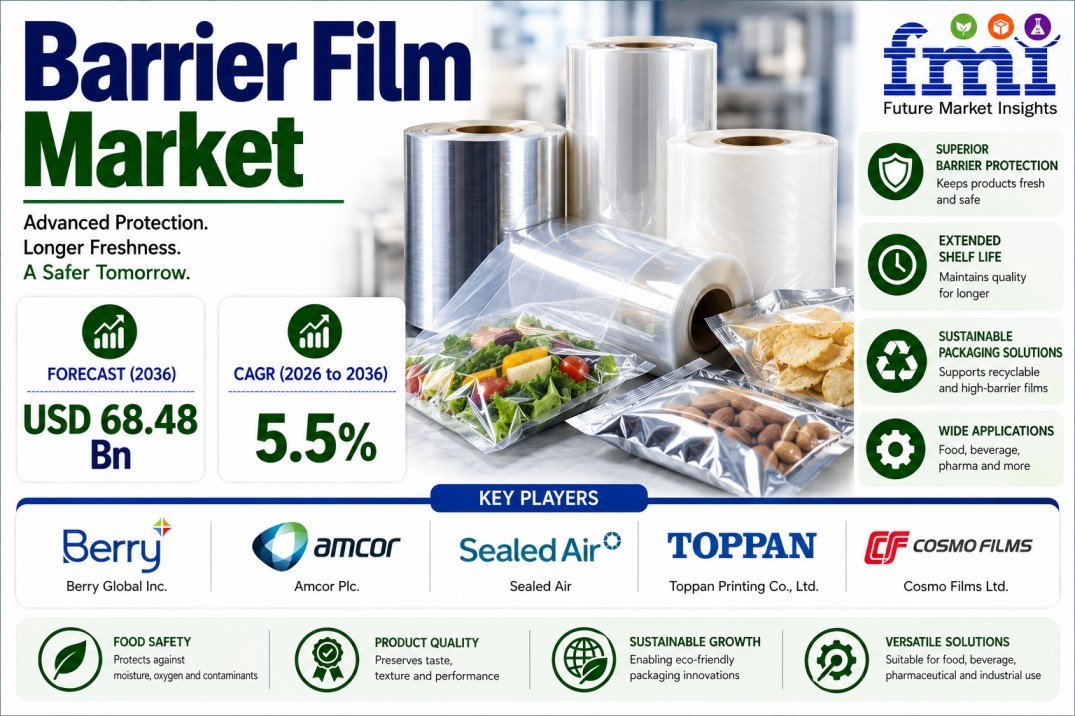
The global barrier film market is projected to reach USD 68.48 billion by 2036, expanding at a 5.5% CAGR from 2026 to 2036, as food, pharmaceutical, and consumer-goods packaging applications increase demand for films that provide moisture, oxygen, aroma, and contamination protection.
The market is shifting toward barrier structures that combine performance with recyclability. Polyethylene (PE) is expected to account for 34.8% of the material type segment in 2026, while high-barrier films represent 36.2% of the product type segment. India and China are forecast to grow faster than the global market, at 5.9% and 5.7%, respectively.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsigh....ts.com/reports/sampl
Why are barrier film specifications changing?
Food manufacturers continue to rely on barrier films to extend shelf life and protect products from moisture ingress, oxygen transmission, and aroma loss. Pharmaceutical and medical packaging creates an additional layer of demand because film structures must meet tighter performance and material-compatibility specifications.
At the same time, sustainability requirements are changing how those performance characteristics are delivered. Traditional multilayer structures can combine polymers and metallized layers that complicate recycling, encouraging film producers to develop mono-material and recyclable alternatives.
This creates a technical challenge for the industry: recyclability cannot come at the expense of the barrier performance required by sensitive products. Suppliers therefore increasingly compete on their ability to engineer material structures that balance shelf-life protection, processability, recyclability, and cost.
The competitive landscape includes Berry Global Inc., Amcor Plc., Sealed Air, Toppan Printing Co., Ltd., Cosmo Films Ltd., Uflex Ltd., Jindal Poly Films Ltd., Mondi Group, Huhtamaki, and ProAmpac.
Which applications and regions are creating the strongest opportunities?
Food packaging remains a major demand center because barrier performance directly affects product shelf life and waste reduction. Pharmaceutical applications add demand for higher-specification structures where packaging integrity and material compatibility are critical.
The regional outlook is particularly notable in Asia. India is forecast to grow at 5.9% CAGR through 2036, followed by China at 5.7%. The USA is projected at 5.1%, while the UK and Germany are expected to grow at 4.8% and 4.7%, respectively.
The faster growth in India and China reflects expanding food-processing and pharmaceutical manufacturing capacity. For suppliers, this creates an opportunity to align regional production and distribution networks with growing demand for performance-oriented packaging materials.
Analyst Perspective
Ismail Sutaria, Principal Consultant at Future Market Insights, says:
“The barrier film market reflects the intersection of packaging protection requirements and sustainability mandates. Producers that can deliver verified barrier performance through recyclable mono-material structures are positioned to capture brand and retailer procurement as sustainability compliance requirements tighten during the forecast period.”
Market Snapshot
• 2026 market size: USD 28.39 billion
• 2036 forecast: USD 68.48 billion
• CAGR, 2026–2036: 5.5%
• Polyethylene (PE): 34.8% of material type segment
• High-barrier films: 36.2% of product type segment
• 1-Octene: 27.0% of chemical type segment
• India CAGR: 5.9%
• China CAGR: 5.7%
Access detailed market insights: https://www.futuremarketinsigh....ts.com/reports/broch
What is driving barrier film demand?
Food shelf-life requirements: Barrier films help control oxygen, moisture, and aroma transmission, supporting longer shelf life across packaged foods.
Pharmaceutical packaging: Sensitive pharmaceutical products require controlled barrier performance and material compatibility, supporting demand for high-specification films.
Sustainability transition: Brands and packaging producers are evaluating mono-material and recyclable structures as alternatives to conventional multilayer architectures.
Material engineering: Development of improved polyolefin, PE, PP, EVOH, PA, and PET structures is expanding the range of barrier-performance options available to packaging producers.
Recycling infrastructure limitations and the technical complexity of replacing multilayer films remain important challenges. Film suppliers must demonstrate that new structures can meet application-specific barrier requirements while also improving end-of-life compatibility.
About the Barrier Film Market Report
The Barrier Film Market study examines barrier films by chemical type, application, material type, and product type across North America, Latin America, Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
The study covers more than 30 countries and evaluates polyethylene, polypropylene, polyamide, EVOH, PET, and other material structures used for engineered barrier applications through 2036.
FMI Research Methodology: https://www.futuremarketinsights.com/methodology
Barrier Film Market: https://www.futuremarketinsigh....ts.com/reports/barri
Portion Sauce Cups with Lids Market: https://www.futuremarketinsigh....ts.com/reports/porti
Germany Returnable Bottle Systems Market: https://www.futuremarketinsigh....ts.com/reports/germa
Ice Bags Market: https://www.futuremarketinsigh....ts.com/reports/ice-b

Disclosure: This press release is based on Future Market Insights' syndicated research. Market estimates and forecasts reflect the definitions, assumptions and methodology applied in the underlying study.

Media Contact
Future Market Insights, Inc.
Christiana Corporate
200 Continental Drive, Suite 401
Newark, Delaware 19713, United States

About Future Market Insights
Future Market Insights, Inc. is a global market intelligence and consulting organization serving clients across more than 150 countries. The company is registered in Delaware as Future Market Insights, Inc., Christiana Corporate, 200 Continental Drive, Suite 401, Newark, Delaware 19713, United States, with regional operations across North America, Europe, the Middle East and India.

image
Beğen
Yorum Yap
Paylaş
Vishal Panchmukh profile picture
Vishal Panchmukh
6 w - çevirmek

Portion Sauce Cups with Lids Market Set to Grow at 4.9% CAGR Through 2036, Saudi Arabia Records 6.6% Growth

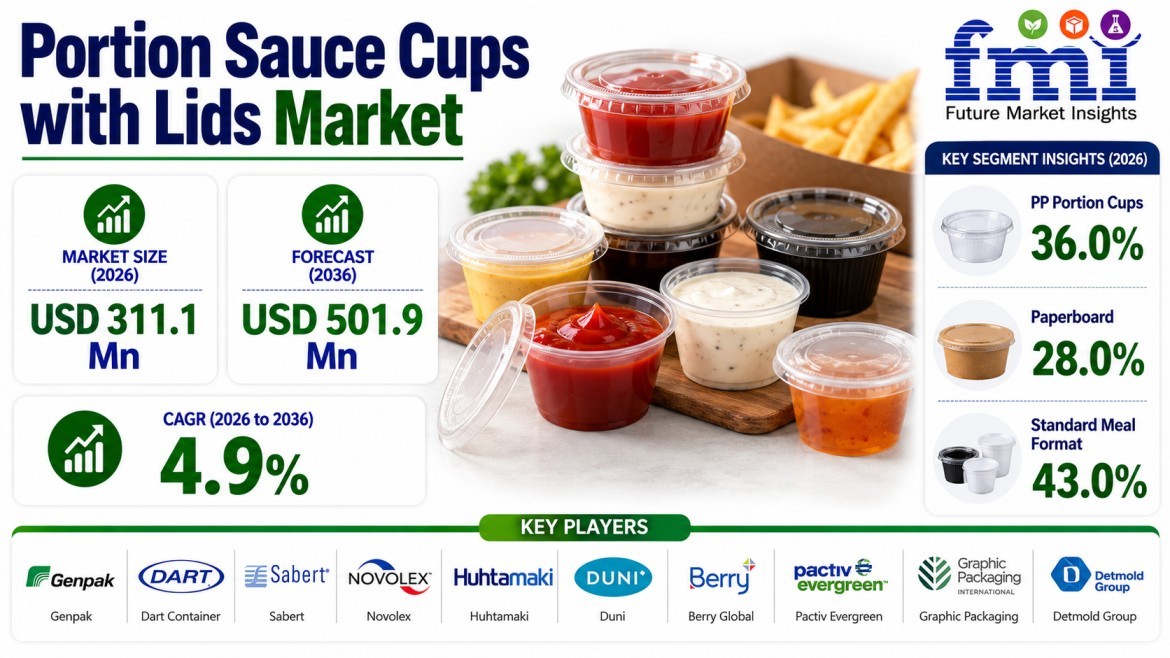
The regulatory shift comes as the global Portion Sauce Cups with Lids Market is projected to grow from USD 311.1 million in 2026 to USD 501.9 million by 2036, representing a 4.9% CAGR.
The market is not moving uniformly toward one replacement material. FMI expects PP portion cups to hold 36.0% of product-type demand in 2026, while paperboard leads the material category at 28.0%. Standard meal formats account for 43.0% of format-size demand, and QSR chains represent 28.0% of end-use demand.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsigh....ts.com/reports/sampl
Why Is the Cup-and-Lid System Becoming More Important Than the Cup Alone?
A condiment cup is inexpensive, but its failure occurs at the point where foodservice operators have the least tolerance for disruption.
A lid that leaks during delivery can create product loss, customer complaints and packaging waste. A cup that denests poorly can slow service. A lower-plastic material that weakens after contact with oily or acidic sauces can create a different form of operational failure.
That is why material substitution is increasingly being evaluated as a cup-and-lid system, rather than as a simple resin replacement.
The market includes Genpak, Dart Container, Sabert, Novolex, Huhtamaki, Duni, Berry Global, Pactiv Evergreen, Graphic Packaging and Detmold Group, with suppliers approaching the opportunity through conventional plastic formats, paperboard, molded fiber and lower-plastic structures.
The distinction is important because a successful alternative must maintain sauce barrier performance, dimensional stability, denesting and closure engagement while also meeting local recovery or regulatory requirements.
How Is Off-Premises Dining Supporting Repeated Demand?
The restaurant industry's shift toward takeaway and delivery provides a recurring consumption base for portion packaging.
The National Restaurant Association reported in April 2025 that nearly 75% of U.S. restaurant traffic occurred off-premises, while 65% of limited-service operators offered delivery. Every separately packed condiment creates another cup-and-lid requirement when sauces cannot be dispensed directly into the meal.
This recurring usage explains why standard meal formats are forecast to represent 43.0% of market demand in 2026. One approved format can support several menu items, simplify inventory and reduce training requirements across multiple locations.
QSR chains are expected to remain the largest end-use category at 28.0%, because standardized menus and repeated order volumes make packaging consistency commercially valuable.
The distribution side matters as well. Broadline foodservice distributors are forecast to hold 33.0% of sales-channel demand in 2026, reflecting the advantage of replenishing packaging alongside other restaurant supplies.
Can Paperboard and Fiber Formats Replace Conventional Plastic Without Raising Leakage Risk?
The transition is possible, but performance remains the qualification gate.
Paperboard is forecast to lead the material category with 28.0% share in 2026. Its appeal comes from a rigid, printable structure with less visible polymer content. However, sauces introduce a demanding combination of oil, acidity, moisture and temperature that can expose weaknesses in coatings or rims.
Huhtamaki's February 2025 ProDairy cup launch, featuring less than 10% plastic and a rim designed for reliable sealing, illustrates the direction of material innovation.
Meanwhile, Berry Global received APR Design for Recyclability recognition for its Versalite polypropylene cups in April 2025, demonstrating that conventional polymer formats are also being redesigned around recyclability.
The competitive implication is clear: material transition does not eliminate the need for performance validation; it increases it.
Analyst Perspective
Nandini Roy Choudhury, Principal Consultant at Future Market Insights, highlights why the physical cup and closure need to be evaluated together:
“Chain operators pay for the cup and lid as one operating system. A cheaper cup loses its advantage if crews fight nested stacks or lids leak in transit. Material conversion should start with sauce barrier and closure force before recovery claims enter the specification.”
What Does the Market Snapshot Show?
• 2026 market value: USD 311.1 million
• 2036 projected value: USD 501.9 million
• 2026–2036 CAGR: 4.9%
• Leading product type: PP portion cups — 36.0%
• Leading material: Paperboard — 28.0%
• Leading format: Standard meal — 43.0%
• Leading end use: QSR chains — 28.0%
• Leading sales channel: Broadline foodservice distributors — 33.0%
• Saudi Arabia CAGR: 6.6%
• UAE CAGR: 6.3%
• United States CAGR: 5.7%
Access detailed market insights: https://www.futuremarketinsigh....ts.com/reports/broch
Where Is Demand Growing Fastest?
FMI's country analysis places Saudi Arabia at 6.6% CAGR, followed by the UAE at 6.3%, South Korea at 6.0%, the United States at 5.7%, the UK at 5.4%, France at 5.1%, Germany at 4.8% and Japan at 4.1%.
The faster Gulf-market growth reflects expanding hospitality and food-delivery activity, while South Korea benefits from a dense rapid-delivery ecosystem. The United States offers scale through restaurant chains and established distributor networks.
European markets face a different purchasing environment, where packaging-volume reporting, producer responsibility and material restrictions can influence the economics of changing a specification.
This creates different routes to growth: volume expansion in faster-growing foodservice markets versus material conversion and compliance-driven replacement in mature markets.
What Is Driving Portion Sauce Cup Demand?
Off-premises ordering: Takeaway and delivery create repeated demand for individual condiment packaging.
QSR standardization: Chain operators value consistent dimensions, fill volumes and lid fit across locations.
Material transition: Paperboard, fiber and compostable systems are gaining attention as alternatives to conventional plastics.
Packaging regulation: Jurisdiction-specific rules can require multiple material specifications across restaurant networks.
Distributor replenishment: Broadline distribution reduces procurement friction by combining packaging with other foodservice supplies.
Operational performance: Denesting, filling speed, barrier performance and lid retention remain critical even when sustainability is the primary reason for conversion.
About the Portion Sauce Cups with Lids Market Report
Future Market Insights' study evaluates the market by product type, material, format size, end use and sales channel.
The analysis covers PP portion cups, paper portion cups, compostable cups and dual-dip formats, alongside paperboard, molded fiber and bagasse, rPET and PP, compostable polymers and aluminium.
Applications include QSR chains, delivery platforms, coffee and beverage operations, institutional catering and retail deli. Geographic analysis covers North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia & Pacific, and the Middle East & Africa.
FMI Research Methodology: https://www.futuremarketinsights.com/methodology
Portion Sauce Cups with Lids Market: https://www.futuremarketinsigh....ts.com/reports/porti
Drink Cans Market: https://www.futuremarketinsigh....ts.com/reports/drink
Utility Cases Market: https://www.futuremarketinsigh....ts.com/reports/utili
Multiwall Bags Market: https://www.futuremarketinsigh....ts.com/reports/multi
Disclosure: This press release is based on Future Market Insights' syndicated research. Market estimates and forecasts reflect the definitions, assumptions and methodology applied in the underlying study.
Media Contact
Future Market Insights, Inc.
Christiana Corporate
200 Continental Drive, Suite 401
Newark, Delaware 19713, United States

About Future Market Insights
Future Market Insights, Inc. is a global market intelligence and consulting organization serving clients across more than 150 countries. The company is registered in Delaware as Future Market Insights, Inc., Christiana Corporate, 200 Continental Drive, Suite 401, Newark, Delaware 19713, United States, with regional operations across North America, Europe, the Middle East and India.

image
Beğen
Yorum Yap
Paylaş
 Daha fazla Mesajları yükle
    Bilgi
  • 17 Mesajları

  • Erkek
  • 12/27/97
    Albümler 
    (0)
    Arkadaşlar 
    (0)
    Beğeniler 
    (60)
  • foodkia.com
    eFoodis
    গ্রামীন ঐতিহ্য
    Child Safety Policy
    SEO Tips and Tricks
    SEO Tips and Tricks
    Hostkia.com
    প্রবাসী কল্যাণ পরিষদ
    অভিযোগ বক্স
    Gruplar 
    (7)
  • ENOOMY Entrepreneur - Start, run and gro
    RANGCON Freelancer Marketplace
    Made in Bangladesh
    অভিযোগ বক্স
    প্রবাসী কল্যাণ পরিষদ
    Buy & Sell Bangladesh
    Search Engine Optimization


© 2026 Justknock Professional Social Networking Platform

Dil

  • Yaklaşık
  • Rehber
  • Blog
  • Bize Ulaşın
  • Geliştiriciler
  • daha
    • Gizlilik Politikası
    • Kullanım Şartları
    • Geri ödeme istemek
    • Child Safety Standards Policy
    • Child Safety Standards

Arkadaşlıktan Çıkar

Arkadaşlık etmek istediğinden emin misin?

Bu kullanıcıyı rapor et

Önemli!

Bu üyeyi ailenden kaldırmak istediğinizden emin misiniz?

poked var 1789670055357587_227950

Yeni üye, aileniz listesine başarıyla eklendi!

Avatarını kırp

avatar

Profil resminizi geliştirin

Kalan bakiye

0

Görüntüler


© 2026 Justknock Professional Social Networking Platform

  • Ana Sayfa
  • Yaklaşık
  • Bize Ulaşın
  • Gizlilik Politikası
  • Kullanım Şartları
  • Geri ödeme istemek
  • Blog
  • Geliştiriciler
  • daha
    • Child Safety Standards Policy
    • Child Safety Standards
  • Dil

© 2026 Justknock Professional Social Networking Platform

  • Ana Sayfa
  • Yaklaşık
  • Bize Ulaşın
  • Gizlilik Politikası
  • Kullanım Şartları
  • Geri ödeme istemek
  • Blog
  • Geliştiriciler
  • daha
    • Child Safety Standards Policy
    • Child Safety Standards
  • Dil

Yorum başarıyla bildirildi.

Mesaj, zaman çizelgesine başarıyla eklendi!

5000 arkadaşınızla ilgili sınırınıza ulaştınız!

Dosya boyutu hatası: Dosya limiti aştı (954 MB) ve yüklenemiyor.

Videonuz işleniyor, ne zaman görüntülenmeye hazır olduğunda size haber vereceğiz.

Dosya yüklenemiyor: Bu dosya türü desteklenmiyor.

Yüklediğiniz resimdeki bazı yetişkinlere uygun içerik tespit ettik, bu nedenle yükleme işleminizi reddetti.

Bir gruptaki yayını paylaş

Bir sayfada paylaş

Kullanıcıya paylaş

Gönderiniz gönderildi, içeriğinizi yakında inceleyeceğiz.

Resim, video ve ses dosyası yüklemek için profesyonel üyeye yükseltmelisiniz. Pro'ya yükselt

Teklifi Düzenle

0%

Katman eklemek


Bir resim seçin
Seviyeni sil
Bu kademeyi silmek istediğinize emin misiniz?

İçeriğinizi ve gönderilerinizi satmak için birkaç paket oluşturarak başlayın. Para kazanma

Cüzdan tarafından ödeme

Adresinizi Sil

Bu adresi silmek istediğinize emin misiniz?

Para kazanma paketinizi kaldırın

Bu paketi silmek istediğinizden emin misiniz?

Abonelikten çık

Bu kullanıcının aboneliğinden çıkmak istediğinizden emin misiniz? Para kazandıran içeriklerin hiçbirini görüntüleyemeyeceğinizi unutmayın.

Para kazanma paketinizi kaldırın

Bu paketi silmek istediğinizden emin misiniz?

Ödeme uyarısı

Öğeleri satın almak üzeresiniz, devam etmek ister misiniz?
Geri ödeme istemek

Dil

  • Arabic
  • Bengali
  • Chinese
  • Croatian
  • Danish
  • Dutch
  • English
  • Filipino
  • French
  • German
  • Hebrew
  • Hindi
  • Indonesian
  • Italian
  • Japanese
  • Korean
  • Persian
  • Portuguese
  • Russian
  • Spanish
  • Swedish
  • Turkish
  • Urdu
  • Vietnamese